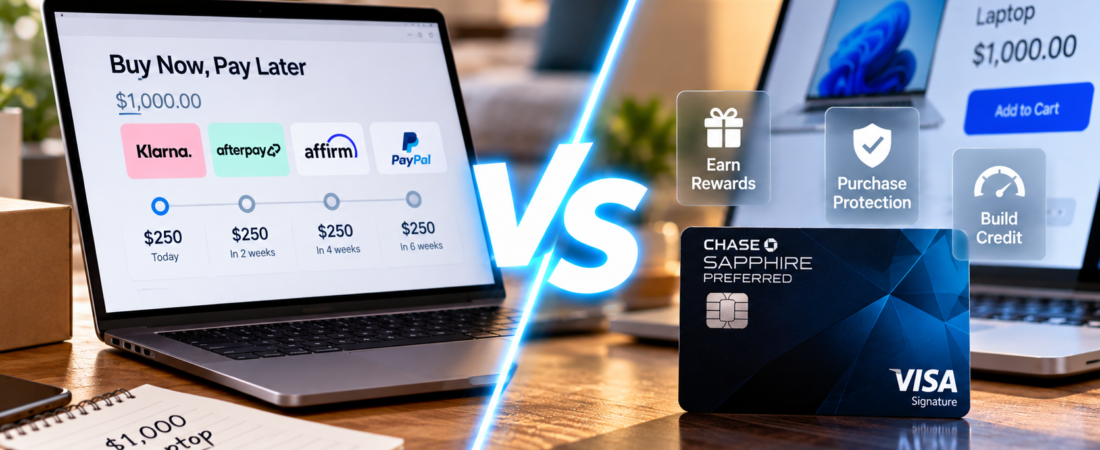
You’re about to buy a $1,000 laptop.
At checkout, you have two options.
Put the entire $1,000 on your credit card.
Or choose Buy Now, Pay Later and split the purchase into several smaller payments.
The second option can feel easier.
Instead of seeing:
$1,000
you might see:
4 payments of $250
The laptop didn’t get cheaper.
But psychologically, the purchase can feel very different.
That’s one reason Buy Now, Pay Later services have become so popular.
Nearly half of Americans surveyed by LendingTree in 2026 said they had used a BNPL service at least once. LendingTree
But when comparing Buy Now, Pay Later vs credit card, the better payment method isn’t simply the one with the smaller payment today.
Interest, rewards, credit reporting, payment timing and purchase protections can all change the calculation.
So let’s use a $1,000 purchase and compare what actually happens.
Buy Now, Pay Later vs Credit Card at a Glance
| BNPL Pay-in-4 | Credit Card | |
|---|---|---|
| Purchase | $1,000 | $1,000 |
| Typical structure | 4 installments | Monthly statement |
| Interest | Often 0% on Pay-in-4 | Can be 0% if paid in full |
| Hard credit inquiry | Often no | Usually when opening card |
| Rewards | Usually none | Possible |
| Flexibility | Fixed installments | More flexible |
| Credit building | Often limited | Generally reported |
| Risk of carrying debt | Short repayment period | Balance can continue |
| Late-payment consequences | Vary by provider | Fees/interest/credit effects possible |
| Purchase protections | Vary | Can be stronger, depending on card |
There isn’t one universal BNPL product or one universal credit card.
Terms vary significantly.
But the basic difference is important:
BNPL usually turns one purchase into a short installment plan.
A credit card gives you a revolving line of credit that can be reused across many purchases.
Scenario 1: $1,000 With Pay-in-4
Suppose the retailer offers a standard interest-free Pay-in-4 plan.
Your $1,000 purchase becomes:
Payment 1: $250
Payment 2: $250
Payment 3: $250
Payment 4: $250
Total:
$1,000
A common Pay-in-4 arrangement divides the purchase into four payments, often made every two weeks. Many such plans don’t charge interest, although exact terms vary by provider. Consumer Financial Protection Bureau
If you make every payment on time:
Purchase price: $1,000
Interest: $0
Total cost: $1,000
That’s very attractive.
You keep more cash temporarily while avoiding interest.
But there’s an important question:
Would you have bought the $1,000 laptop if the checkout page simply asked you for $1,000?
That’s where BNPL becomes more complicated.
Scenario 2: $1,000 on a Credit Card and Pay It Off
Now put the same laptop on a credit card.
Charge:
$1,000
Then pay the full statement balance by the due date, assuming your card has a grace period and you aren’t already carrying a balance in a way that eliminates it.
Interest:
$0
Total purchase cost:
$1,000
So in this scenario:
BNPL = $1,000
Credit card = $1,000
Financially, they’re essentially tied on the purchase price.
But a rewards credit card could change the result slightly.
What If the Credit Card Gives 2% Cash Back?
Suppose your card earns:
2% cash back
$1,000 × 2% =
$20
If you pay the statement balance in full and avoid interest, your effective net cost after rewards could be approximately:
$980
Now the credit card has a potential advantage.
BNPL generally isn’t offering you $20 simply for using it.
But this advantage disappears very quickly if you carry the credit-card balance and start paying interest.
Scenario 3: You Can’t Pay the Credit Card Off
This is where the comparison changes dramatically.
Suppose you put $1,000 on a credit card but don’t have enough money to pay the statement balance in full.
Now you’re borrowing money at the card’s APR.
The exact cost depends on:
Your APR.
Payment amount.
Existing balance.
Timing.
And how quickly you repay it.
A $20 cash-back reward suddenly isn’t very important if you’re paying substantial interest over several months.
This is one of the biggest mistakes people make with rewards cards.
They focus on:
2% cash back
while ignoring:
20%+ borrowing costs.
Rewards are useful when you’re paying the balance off.
They’re much less meaningful when you’re carrying expensive revolving debt.
BNPL Forces a Repayment Schedule
This can actually be an advantage.
With Pay-in-4, the repayment structure is usually predetermined.
You don’t get to say:
“I’ll just make the minimum payment this month.”
Your $1,000 purchase might require:
$250 today.
$250 in two weeks.
$250 two weeks later.
$250 two weeks after that.
Then you’re done.
A credit card is more flexible.
But flexibility can be dangerous.
The minimum-payment system allows debt to survive month after month.
BNPL’s short schedule can force you to confront the real cost of the purchase quickly.
But BNPL Creates a Different Problem
The payments look small.
$250 sounds much easier than $1,000.
Now imagine you buy:
Laptop: $1,000
Shoes: $200
Airline ticket: $600
Furniture: $800
Each purchase has its own installment schedule.
Individually, everything may look manageable.
Together, you suddenly have multiple automatic payments hitting your account at different times.
This is called loan stacking, and it’s one of the more important BNPL risks.
CFPB research found that more than three-fifths of BNPL borrowers in its studied population had simultaneous BNPL loans at some point during the year examined. Consumer Financial Protection Bureau
That’s very different from looking at a single $250 payment.
2026 Data Shows Why This Matters
LendingTree’s March 2026 survey found that 47% of BNPL users surveyed said they had paid late on a BNPL loan at least once during the previous year.
That was up from 41% in 2025 and 34% in 2024. LendingTree
The same survey found:
25% of BNPL users said they had held three or more BNPL loans simultaneously.
And:
68% agreed that BNPL loans caused them to overspend. LendingTree
These are self-reported survey results, so they shouldn’t be interpreted as saying 47% of every BNPL account becomes delinquent.
But they illustrate the behavioral risk.
The problem may not be one $1,000 laptop.
The problem may be having six “small” installment plans at the same time.
Credit Cards Make Your Total Debt Easier to See
Suppose you make four purchases totaling:
$2,500
on one credit card.
Your account shows:
Balance: $2,500
That’s uncomfortable.
But it’s clear.
Now imagine those same purchases spread across:
Klarna.
Affirm.
Afterpay.
PayPal.
Each app may show a manageable-looking payment.
Your brain has to reconstruct the total obligation.
That’s one reason BNPL can make debt feel smaller than it actually is.
The purchase hasn’t become cheaper.
The interface has changed how the cost is presented.
What About Credit Scores?
This area is more complicated than many people assume.
Credit cards are typically reported to the major credit bureaus.
That means:
Payment history.
Credit utilization.
Account age.
And other factors associated with the account can affect your credit profile.
Traditional Pay-in-4 BNPL has historically worked differently.
CFPB consumer guidance says most Pay-in-4 BNPL products generally don’t report regular payment history to the major credit reporting companies, although practices vary and other installment products can work differently. Consumer Financial Protection Bureau
That means successfully paying four installments may not help build credit the same way responsible credit-card use can.
However, failure to repay BNPL debt can still create problems.
If unpaid debt is sent to collections and reported, it may damage your credit. Consumer Financial Protection Bureau
So don’t assume:
“BNPL doesn’t affect credit.”
The more accurate answer is:
It depends on the product, provider and what happens with the account.
Always check the specific terms.
What About Applying?
Another BNPL advantage is convenience.
Many Pay-in-4 products generally don’t require the kind of hard credit inquiry associated with applying for a traditional credit card. Consumer Financial Protection Bureau
That can make approval fast.
But longer-term installment financing offered through some BNPL companies can operate differently.
A six-, twelve- or twenty-four-month financing plan isn’t necessarily the same product as interest-free Pay-in-4.
That’s an important distinction.
“BNPL” doesn’t automatically mean “0% interest.”
Always look at the APR and total repayment amount.
Purchase Protection Can Favor Credit Cards
Suppose your $1,000 laptop never arrives.
Or arrives damaged.
Or you discover an unauthorized charge.
Credit cards operate within a mature consumer-protection framework and provide established billing-dispute rights.
The CFPB maintains specific guidance for disputing credit-card charges and dealing with unauthorized transactions. Consumer Financial Protection Bureau
BNPL protections and processes can vary more by provider and product.
The regulatory treatment of BNPL has also been changing: the CFPB withdrew its 2024 BNPL interpretive rule in May 2025. Consumer Financial Protection Bureau
That makes it especially important to read the current terms of the specific BNPL service rather than assuming it works exactly like a credit card.
Returns Can Also Become More Complicated
Imagine:
You buy a $1,000 laptop.
Pay the first $250 installment.
Return the laptop.
Now three parties may be involved:
You.
The retailer.
The BNPL provider.
The retailer processes the return.
The financing provider has the payment schedule.
Refund timing and procedures can vary.
With a credit card, returns aren’t always instant either, but the transaction generally stays within the familiar card ecosystem.
The more layers involved in a transaction, the more important it becomes to understand how refunds are handled.
The Biggest BNPL Advantage: Interest-Free Cash Flow
Used carefully, Pay-in-4 has a legitimate benefit.
Suppose you have $10,000 sitting in your checking account.
You could easily pay $1,000 today.
But the retailer offers:
$250 × 4
with no interest or fees.
You keep more of your cash temporarily.
If you’re disciplined and the money is already available, that’s useful flexibility.
You’re effectively spreading the timing of the expense without increasing its price.
But notice the key condition:
You already had the money.
That’s very different from using BNPL because you can’t afford the $1,000 purchase.
The Biggest Credit Card Advantage: Rewards + Protection + Simplicity
Now consider the disciplined credit-card user.
Buy laptop:
$1,000
Earn 2%:
$20
Pay statement:
$1,000
Interest:
$0
Potential net reward:
$20
And all your purchases appear in one account.
Depending on the card, you may also receive additional purchase protections, extended warranties or other benefits.
For someone who consistently pays the full statement balance, a rewards credit card can be an extremely efficient payment tool.
The danger begins when:
“I’ll pay it off next month.”
becomes:
“I’ll pay it off eventually.”
What If the Credit Card Offers 0% APR?
There’s another option.
Some credit cards offer promotional:
0% APR
for a defined introductory period.
Now the card may combine several BNPL-like advantages with the flexibility of a credit line.
For example:
$1,000 purchase.
0% introductory APR.
Rewards may also be available depending on the card.
But this creates another temptation.
Pay-in-4 forces relatively fast repayment.
A long 0% promotional period can make it easier to postpone repayment.
And once the promotional period ends, the account’s regular APR rules apply.
The correct question isn’t simply:
“Is the APR 0% today?”
It’s:
“Will I have the entire balance paid before the promotional period ends?”
When BNPL Can Make Sense
BNPL can be useful when:
- It’s genuinely 0% interest.
- There are no fees if you pay as agreed.
- You already have enough money for the purchase.
- You want to spread cash flow over several weeks.
- You’re comfortable with automatic payments.
- You aren’t juggling multiple installment plans.
- The purchase fits comfortably within your budget.
In that situation, BNPL is primarily a payment-timing tool.
When a Credit Card Can Make Sense
A credit card can be attractive when:
- You pay the statement balance in full.
- You earn meaningful rewards.
- You value established dispute procedures.
- You want purchases consolidated into one account.
- You’re building a credit history.
- Your card offers useful purchase benefits.
- You carefully track your spending.
Again, the key is avoiding expensive revolving debt.
The Most Important Question Comes Before Either Option
Before asking:
BNPL or credit card?
ask:
Would I still buy this if I had to pay $1,000 in cash today?
That’s an extremely useful test.
If the answer is:
“Yes. I have the money. I’m simply choosing the best payment method.”
then you’re comparing payment tools.
If the answer is:
“No. I can only afford it because the payment looks like $250.”
then the financing may be changing the purchase decision itself.
That doesn’t automatically make the purchase wrong.
But it means the more important comparison may be:
Buy now vs wait.
Buy Now, Pay Later vs Credit Card: Which Is Better for $1,000?
Consider three simplified situations.
BNPL Pay-in-4
Purchase: $1,000
Interest: $0
Rewards: $0
Total paid: $1,000
2% Rewards Credit Card Paid in Full
Purchase: $1,000
Interest: $0
Rewards: $20
Potential effective net cost after rewards: $980
Credit Card With Balance Carried
Purchase: $1,000
Rewards: perhaps $20
Interest: depends on APR and repayment time
Potential total cost: more than $1,000
That’s why there isn’t one winner.
For someone who always pays the statement balance in full, a good rewards credit card can offer compelling benefits.
For someone who wants a short, predictable 0% repayment schedule and can comfortably make every installment, Pay-in-4 can be useful.
For someone who needs either option simply because the purchase isn’t affordable today, the most important number may not be the installment amount or the credit-card minimum.
It’s still:
$1,000.
Splitting the price changes when you pay.
It doesn’t change what you bought.
Compare with Reason.